5 Smart Money Moves to Future-Proof Your Family’s Finances
Preparing for your family’s future isn’t just about earning more—it’s about making smarter money choices today.
Published on Sep 17, 2026
When you're raising a family, money has a funny way of disappearing. We often hear our moms and dads describe their salaries this way: “dumaan lang sa palad” or “naglahong parang bula.”
We’ve been there once or twice–the grocery run that somehow goes over budget, school expenses that seem to arrive one after another, bills, birthdays, medical emergencies, and the occasional “Mama, can we buy this?” that you weren't exactly prepared for. Then there are the bigger dreams: a home to call your own, your children's education, family vacations, that business you’ve always dreamed about, and eventually retiring without having to depend on your children financially.
Indeed, it's a lot to think about.
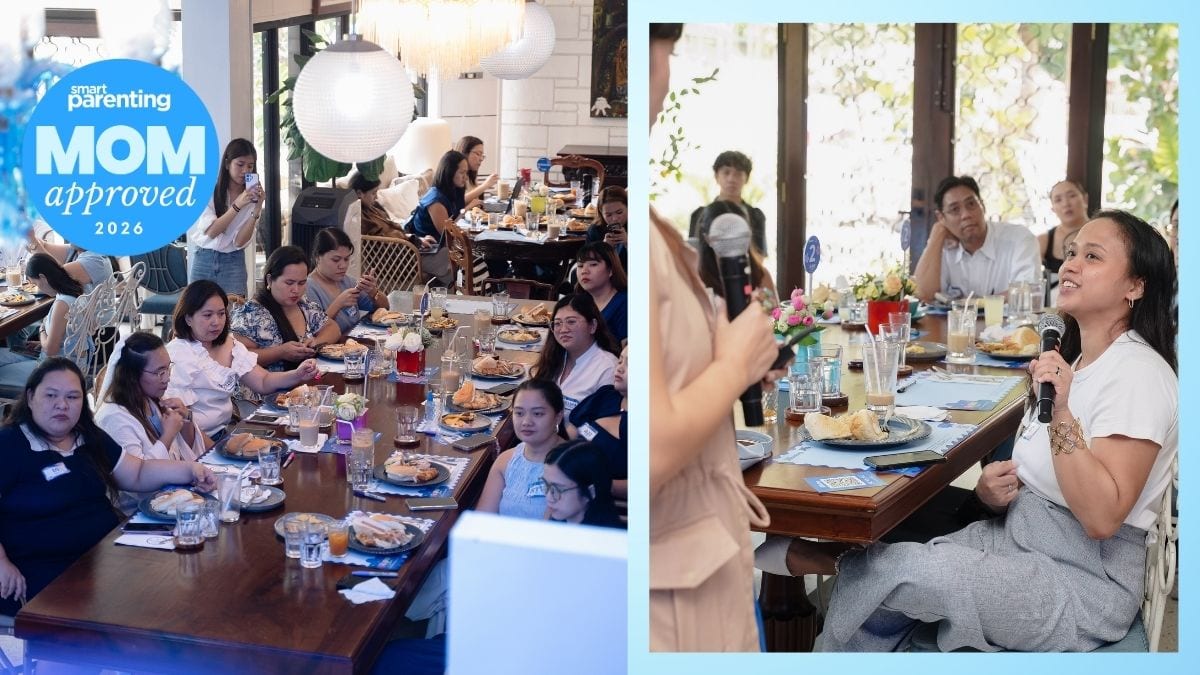
Last Sunday, September 6, Smart Parenting took its first step into a new kind of learning experience for the parents of Smart Parenting Village, with its very first Smart Parenting Weekend Workshop. In partnership with SKIPPY® Brand, the initiative was held at the event’s official venue partner, Timezone, where parents came together for a day of practical conversations about money, shared experiences, and lessons that go beyond the everyday challenges of raising a family.
One of the highlights of the event was a financial literacy workshop conducted by the Bank of the Philippine Islands (BPI), which explored a topic many parents think about but may not always know how to approach: how to future-proof the family’s finances.
Smart Parenting Editor-in-Chief Ronna Capili-Bonifacio extended her warm welcome to the attendees and opened the learning session with a thought provoking statement so that we, as a new generation of parents, flip the script and move away from the popular narrative that children are meant to be the retirement fund. She yearned, “I hope that today, you are also able to be one step closer to the kind of parent and the kind of family that you want to build.”
5 Ways to Future-Proof Your Family’s Finances
At the Weekend Workshop, financial expert and BPI team head of Global Markets Retail Sales for South Luzon, Chrizel Dimaunahan led the discussion on setting financial goals, budgeting, saving, and investing. Dimaunahan also introduced a different meaning for BPI: Basic and Practical Investing.
Backed by over 15 years of banking experience, she shared practical ways families can become more intentional about their money.
Here are five things parents can begin doing now.
1. Know what you're actually saving for
It's easy to say, “I need to save more.” But save for what? Dimaunahan encouraged attendees to “always start with an end in mind.” In other words, be specific about your goals.
Is it for travel? Your child's college education? An emergency fund? Starting a business? A down payment on a home? Retirement?
Knowing your goal gives your money direction and helps you budget accordingly. “Setting a goal is one thing; getting there is another,” Dimaunahan said.
The workshop introduced a simple way of looking at your financial goals called YOLO: Years, Objective, Limits, and Orientation. To put that into practice, you can ask yourself: When will I need the money–this year, next year, or in five years? What exactly am I saving or investing for? And how familiar am I with investing?
For parents, this can be especially helpful because not every financial goal has the same timeline. Money you'll need soon shouldn't necessarily be treated the same way as money you're setting aside for something 10 or 15 years from now.
The first step isn't necessarily finding the “best” investment. It's knowing exactly where you're going.
2. Build a financial safety net before chasing bigger returns
As parents, we know that the unexpected doesn't exactly ask for permission before showing up.
“Biglang nawala ang income for two months, ano ang sasalo?” Dimaunahan challenged the crowd. The attendees almost immediately responded with “emergency funds.”
According to Dimaunahan, an emergency fund should cover at least six months of essential expenses—including food, rent or housing payments, loans, tuition, and other necessary household costs.
Think of it as your family's “just in case” fund.
And there's something comforting about knowing that if life suddenly throws you a curveball, you don't have to immediately reach for a credit card or borrow money from someone else just to get through it. Before we worry about making our money grow, we need to make sure we have something to fall back on when unforeseen circumstances arise.
3. Don't let all your money sit in one basket: Diversify
We've all probably heard the saying, “Don’t put all your eggs in one basket.” Saving is important, but simply keeping all your money in one place may not always be enough to meet long-term goals.
Why? Because of inflation.
The purchasing power of money can decrease over time as prices rise. That P100,000 you've carefully saved today won't necessarily buy the same things years from now. This is where investing can become part of a family's long-term financial strategy.
According to Dimaunahan, “Investing is for potential returns to beat inflation. Kakainin lang ng inflation ‘yung savings natin kung nandyan lang siya.”
This is where diversification comes in. It is an investment strategy that aims to maximize earning potential while managing risk. Just as we wouldn't want to put all our eggs in one basket, we may not want every peso earmarked for the future to depend on a single type of asset.
Dimaunahan discussed deposits, equities, stocks, and bonds. You can think of each as a different “basket.”
Of course, investing also comes with risks, and the right choice depends on your goals, timeline, and comfort with risk. Before putting money into any investment, understand what you're buying, where your money goes, how long it will be invested, and what risks you're taking. It is also important to remember that everyone has a different level of risk tolerance.
Don't invest simply because someone says, “Kumikita ako dito.” Take the time to understand the bigger picture, too.
4. Make saving a habit—not what's left over at the end of the month
The old formula, according to Dimaunahan, is income minus expenses equals savings. For her, the new formula is income minus savings equals expenses, or the money available to spend.
It's easier said than done, especially when grocery prices, utility bills, school expenses, and everything else keep creeping up. But saving first—even a manageable amount—turns saving from something we hope to do into something we intentionally make room for.
That could mean eating out less often, cutting back on unnecessary online purchases, or finding simple ways to reduce everyday expenses. But it doesn't have to mean depriving the family of every little joy. It's about deciding which things are worth spending on today and which goals are important enough to save for tomorrow.
According to Dimaunahan, “...ang tinitarget natin is discipline, may muscle tayo na ini-i-stretch for saving and investing.”
5. Check your financial plan as your family changes
According to Dimaunahan, there are three investment strategies based on when you need your money:
Bullet strategy: Investments are aligned to mature around one specific future date, such as when your child turns 18 and you need funds to help cover education expenses.
Barbell strategy: This combines short-term investments that provide liquidity when needed with long-term investments intended for future goals, with little in between.
Ladder strategy: This spreads investments across different maturity dates, allowing funds to become available at regular intervals rather than all at once.
The financial plan that worked for your family five years ago may no longer work today. Your children grow. Tuition changes. Your income may change. Your priorities change. You may suddenly have a new goal—or a new expense you didn't anticipate. That's why financial planning shouldn't be a one-time activity.
The workshop emphasized the importance of reassessing and rebalancing your financial portfolio and budget as your family's needs change. Dimaunahan also noted that investments don’t have to be limtied to Philippine peso-dominated assets, depending on your goals and risk profile, foreign currency investments may also be an option.
You can ask yourself: “Are we still on track? Are our savings enough? Are our investments aligned with our goals? Have our priorities changed? Did something happen globally that weakened our purchasing power?”
For Dimaunahan, it’s simple: Reassess. Rebalance. Always live within your means.
Key takeaway: Start with your goals, then build your financial habits around them.
Future-proofing your family's finances isn't about becoming wealthy overnight or knowing exactly what the market will do next. It's about creating habits that give your family options when life doesn't go according to plan.
Because parenting isn't only about making sure our children have what they need today. It’s also about quietly preparing for the big things we hope they’ll have tomorrow—from their education and future goals to unexpected expenses and, eventually, financial independence. And part of that preparation means breaking away from the notion that children should be treated as investments or their parents’ retirement funds.
In the end, it’s about taking that first step toward a more prepared future. Sometimes, that simply starts with learning together—alongside a village of parents who are figuring it out, too.
On that note, we hope to see you at our next Smart Parenting Weekend Workshop, because you don’t have to navigate parenting alone.
This Smart Parenting Weekend Workshop is co-presented with SKIPPY® Brand, with BPI as partner and Timezone as official venue partner.
Moms spill their kids’ baon favorites—and what really gets eaten.
From Newborn to Toddler: A Diaper Parents Trust Most
Read hereA doting mother of two, April finds her greatest joy in traveling to new places with her family. When she's not chasing new horizons or penning down her thoughts, she channels her creativity into cooking, baking, or getting lost in the pages of a beloved book.
Read more stories about